UK business audit process

Audit Process for UK Business Owners | Thresholds, Stages & Cost

Table of Contents

If you run a limited company and someone has mentioned the word “audit”, this guide tells you what it actually involves, whether you need one, what it costs, and how to get through it without losing a fortnight. It is written for business owners, not auditors, and it reflects the UK rules that changed on 6 April 2025.

What is a company audit?

A company audit is an independent examination of your financial statements by a registered auditor, who then gives a written opinion on whether those statements show a “true and fair view” of the business. In the UK, this is called a statutory audit, because it is required by the Companies Act 2006 for companies above a certain size.

An audit is not a check of every invoice. The auditor plans their work around risk, tests samples of transactions and balances, examines the systems that produce your numbers, and forms an opinion. The output is the auditor’s report, which sits inside your annual accounts and is filed at Companies House alongside them.

The auditor is working for your shareholders, not for you as a director. That distinction matters: their job is to give an independent view, which is exactly why lenders, investors and buyers place weight on it.
Does my company need an audit?

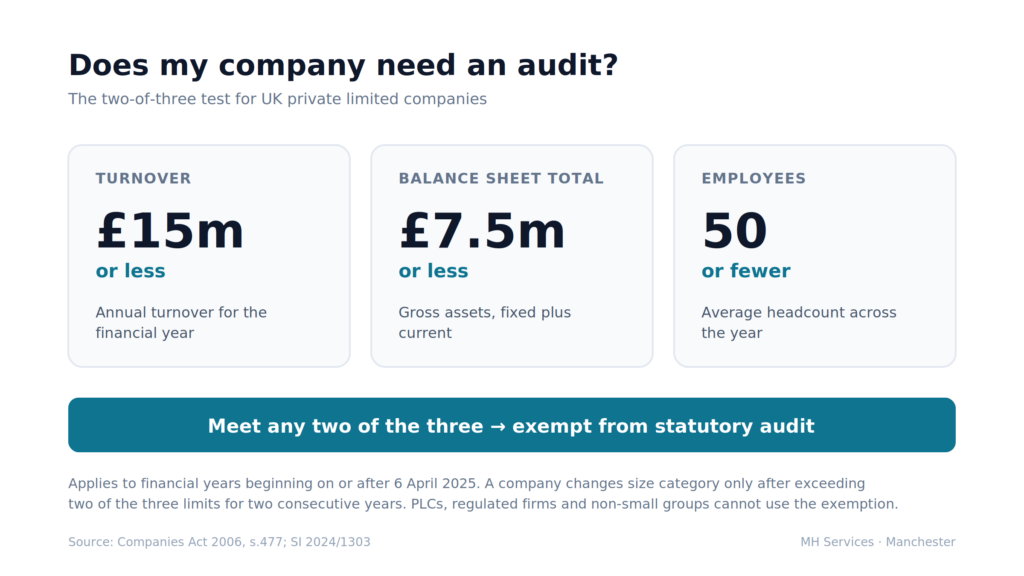
Most UK small companies do not. For financial years beginning on or after 6 April 2025, a private limited company is exempt from a statutory audit if it meets at least two of these three tests:

  • Annual turnover of £15 million or less
  • Balance sheet total (gross assets) of £7.5 million or less
  • An average of 50 or fewer employees

These are the “small company” limits set by the Companies (Accounts and Reports) (Amendment and Transitional Provision) Regulations 2024. They replaced the previous figures of £10.2 million turnover and £5.1 million balance sheet, which had stood since 2016. The employee limit did not change.

Three details catch people out:

  1. The two-year rule. You do not lose exemption the first year you cross the limits. A company only changes size category when it exceeds two of the three tests for two consecutive financial years. Equally, a company that has been having audits does not become exempt until it has met the small-company tests for two consecutive years.
  2. The thresholds depend on when your financial year started. A company with a year running 1 January to 31 December 2025 is still measured against the old limits, because that year began before 6 April 2025. The new limits first apply to the year beginning 1 January 2026. A company with a 31 March year end gets the new limits from the year ending 31 March 2026.
  3. Some companies need an audit regardless of size. You cannot use the small-company exemption if the company is:
  • A public limited company (PLC)
  • A bank, insurer, e-money issuer or certain other FCA-regulated firms
  • Part of a group that, taken as a whole, is not small (the tests are applied to the group, not just your company)
  • Required to have an audit by its own articles of association
  • Asked to have one by shareholders holding 10% or more of the shares, by written notice at least one month before the year end

If you use the exemption, your balance sheet must carry a statement confirming the company was entitled to it. Your accountant will include this.

Worked example: three Manchester companies

Company A — a precision engineering firm in Trafford Park. Turnover £11 million, balance sheet total £6 million, 38 employees. Under the old limits it exceeded both turnover (£10.2m) and balance sheet (£5.1m), so it needed an audit. Under the new limits it meets all three tests. Once it has met them for two consecutive years, it can claim exemption and stop having a statutory audit.

Company B — a logistics business in Salford. Turnover £16 million, balance sheet total £7 million, 45 employees. It exceeds the turnover limit but meets the other two. Because it only needs to pass two of three, it still qualifies as small and is exempt.

Company C — a growing software company in the city centre. Turnover £16 million, balance sheet total £8 million, 45 employees. It exceeds two of the three tests. If it does so for two consecutive years, it becomes a medium-sized company and a statutory audit is required.

The lesson from Company C: if you are close to two of the limits, plan for it. An audit takes weeks, not days, and your first one is always the hardest.

The five stages of an audit process

An audit follows a set path. Knowing what happens at each stage — and what the auditor will ask you for — removes most of the stress.

1. Planning

The auditor gets to know your business, your industry, your systems and where the risks sit. They set a materiality level (the size of error that would matter to a reader of the accounts) and decide which areas need the most attention. Expect a planning meeting and a list of information requests, usually a few weeks before the year end or shortly after it.

What they’ll ask for: last year’s accounts, management accounts, an organisation chart, a description of how sales, purchases and payroll are processed, and details of any unusual events during the year.

2. Fieldwork

This is the main body of the audit. The auditor tests transactions and balances: confirming bank balances directly with your bank, sampling sales invoices back to contracts and cash received, checking that stock exists and is valued correctly, agreeing fixed assets to invoices, and reviewing debtors for anything unlikely to be paid. 

For a single-entity company with turnover between £1 million and £15 million, fieldwork typically takes five to fifteen working days, on site or remotely.

What they’ll ask for: bank statements, sales and purchase ledgers, aged debtor and creditor lists, fixed asset register, stock records, payroll reports, VAT returns, loan agreements, leases and board minutes.

3. Analysis and evaluation

The auditor pulls the evidence together, reviews the accounting judgements you have made (depreciation rates, bad debt provisions, revenue recognition, going concern), and decides whether any adjustments are needed. This is where most discussion happens between you and the audit team.

4. Reporting

The auditor issues their report. There are four possible opinions:

  • Unmodified (clean) — the accounts give a true and fair view. This is what almost every well-run company receives.
  • Qualified — the accounts are fine except for one specific matter, which the report describes.
  • Adverse — the accounts are materially misstated. Rare and serious.
  • Disclaimer — the auditor could not get enough evidence to form an opinion at all.

Alongside the formal report, most auditors provide a management letter setting out weaknesses they noticed in your controls and how to fix them. This is often the most useful document the audit produces.

5. Follow-up

You act on the management letter, the accounts are approved by the board and filed at Companies House (within nine months of the year end for a private company), and the auditor carries the findings forward into next year’s planning. Fix the points raised; the same weaknesses appearing two years running does not look good.

Total elapsed time: usually eight to twelve weeks from planning to signed report, driven mostly by how quickly you provide information.

What types of audit are there?

The word “audit” covers several different things. The one most business owners mean is the statutory financial audit, but it helps to know the others.

Four types of audit compared: statutory audit (mandatory above thresholds, for shareholders and lenders), internal audit (voluntary, in-house, for management), compliance audit (rules-based, for regulators and funders), performance audit (efficiency-focused, for owners planning a change).

  • Statutory (financial) audit. The Companies Act audit of your annual accounts by a registered auditor, described above. Mandatory above the size thresholds.
  • Internal audit. A review carried out by people inside the business (or an outsourced team reporting to management) to test whether controls and processes are working. It is not independent in the statutory sense and does not produce an opinion for Companies House, but it is invaluable for catching problems early. Larger companies run an internal audit function; smaller ones often do a lighter version through their finance manager or external accountant.
  • Compliance audit. Checks whether the business is following specific laws, regulations or contract terms — for example a grant audit, a pension scheme audit, or a check on FCA conduct rules.
  • Performance (or operational) audit. Looks at whether a process is efficient and effective rather than whether the numbers are right. Useful before a sale, an expansion, or a systems change.

Internal vs external audit — the real difference

The difference is independence. An external auditor is a registered firm with no employment relationship with the company, and their opinion carries legal weight. An internal auditor works for management, focuses on whichever areas management chooses, and their findings are for internal use.

Internal audit is cheaper and faster and can be pointed at any weak spot. Its limitation is exactly that closeness: it cannot give outsiders the assurance that an independent opinion gives. Most growing companies benefit from both — internal checks through the year, external audit at the year end.

Who can carry out an audit in the UK?

Only a registered auditor can sign a statutory audit report in the UK. This is a firm (or individual) registered with one of the Recognised Supervisory Bodies — the ICAEW, ACCA, ICAS or Chartered Accountants Ireland — and subject to their inspection regime. The report is signed by a named Senior Statutory Auditor on behalf of the firm.

This matters because the term “accountant” is not protected. Many excellent accountancy practices do not hold audit registration, because most of their clients are exempt and the registration involves significant regulatory cost. 

If your accountant is not a registered auditor, they can prepare your accounts and tax returns as normal, but a separate registered firm will need to carry out the audit. The two often work together, and a well-organised accountant makes the auditor’s job — and your fee — smaller.

When choosing an auditor, ask: Are you audit-registered, and with which body? Who will be the Senior Statutory Auditor on my engagement? Have you audited businesses in my sector? What is included in the fee, and what triggers extra charges?

How to prepare for your first audit?

The single biggest factor in how long an audit takes, and what it costs, is how ready you are. A checklist:

Before the year end

  • Agree the timetable and information list with the auditor.
  • Reconcile every bank account and clear old unreconciled items.
  • Chase old debtors and decide which balances need a provision.
  • Count stock at the year end (the auditor may want to attend).
  • Make sure fixed asset additions and disposals are recorded, with invoices filed.
  • Get loan statements, lease agreements and any legal correspondence together.

After the year end

  • Produce a full trial balance and draft accounts as early as you can.
  • Prepare schedules that support each significant balance: debtors, creditors, accruals, prepayments, fixed assets, stock.
  • Have the board minutes and shareholder register up to date.
  • Nominate one person as the auditor’s point of contact.

During the audit

  • Answer requests promptly. Every day of delay is a day of fee.
  • Keep a shared log of outstanding items.
  • Be open about judgement calls. Auditors deal far better with a clearly explained estimate than with one they have to reverse-engineer.

A company that walks in with reconciled ledgers, supporting schedules and a named contact will typically have a shorter, cheaper and calmer audit than one that hands over a shoebox.

What are internal controls?

Internal controls are the processes a company puts in place to make sure its financial information is accurate, its assets are protected, and its people follow the rules. Auditors test them because strong controls mean the numbers can be trusted, which reduces the amount of detailed testing they need to do.

The framework almost every auditor uses (COSO) describes five components. In a small business they look like this:

The five components of internal control (COSO) applied to a small business: control environment, risk assessment, control activities, information and communication, and monitoring. Principle: no single person should raise, approve, pay and record a transaction alone.

Good controls are not about bureaucracy. In a small company they often come down to one principle: no single person should be able to raise, approve, pay and record a transaction on their own.

Should I have an audit even if I’m exempt?

Sometimes, yes. A voluntary audit is worth considering if:

  • A lender or investor wants one. Bank covenants, private equity investors and grant bodies often require audited accounts whatever the company’s size.
  • You are planning to sell the business. Buyers pay more, and negotiate less, for numbers that have been independently verified for the last two or three years.
  • You have external shareholders who are not involved day to day. An audit gives them comfort and reduces disputes.
  • You want to tighten up. The management letter from a first audit frequently identifies weaknesses the owner never knew existed.
  • You are close to the thresholds. Starting a year early means your first mandatory audit is not also your first ever audit.

If none of these apply, the money is often better spent on stronger management accounts and a good accountant.

How much does an audit cost?

For a straightforward single-entity UK company with turnover between £1 million and £15 million, statutory audit fees in 2026 typically fall between £6,000 and £12,000 plus VAT.

Group structures, regulated sectors and overseas operations move that towards £15,000 to £35,000. Fees across the profession have risen since 2024 as regulatory inspection has tightened.

MH Services audits for small and medium-sized companies in Greater Manchester start from £1,000 plus VAT.

Four things drive the price:

  • Turnover and transaction volume — more transactions, more testing.
  • Complexity — group companies, foreign currency, stock, long-term contracts and revenue recognition judgements all add work.
  • Sector — regulated or specialised sectors need auditors with the right expertise.
  • Your preparation — a clean, reconciled set of records can knock days off the fieldwork.

Get the fee basis in writing, including what counts as “additional work” and how it will be charged.

Frequently asked questions

WHAT IS THE AUDIT THRESHOLD IN THE UK FOR 2026? 

A private company is exempt from audit if it meets at least two of: turnover of £15 million or less, balance sheet total of £7.5 million or less, and 50 or fewer employees. These apply to financial years beginning on or after 6 April 2025.

HOW LONG DOES A COMPANY AUDIT TAKE? 

Usually eight to twelve weeks from planning to signed report for a small or medium company, with five to fifteen days of fieldwork. Well-prepared companies sit at the shorter end.

CAN MY ACCOUNTANT DO MY AUDIT? 

Only if they are a registered auditor. Many accountancy practices are not, in which case a separate registered firm carries out the audit while your accountant continues to prepare the accounts.

WHAT IS THE DIFFERENCE BETWEEN AN AUDIT AND A REVIEW? 

An audit gives a positive opinion that the accounts show a true and fair view, based on detailed testing. A review is a lighter, limited-assurance engagement that only reports whether anything came to the accountant’s attention suggesting a problem. Reviews are cheaper but carry much less weight.

WHAT HAPPENS IF MY COMPANY NEEDS AN AUDIT AND DOESN’T HAVE ONE? 

The accounts will not be compliant with the Companies Act. Companies House can reject them, the directors can face penalties, and lenders or shareholders may have grounds to challenge the accounts. If you think you may have crossed the thresholds, speak to an auditor early.

DO I NEED AN AUDIT IF MY COMPANY IS DORMANT? 

No. Dormant companies are exempt from audit provided they meet the dormancy conditions and file dormant accounts.

IS AN AUDIT THE SAME AS AN HMRC INVESTIGATION?

No. An audit is an independent review of your accounts for shareholders. An HMRC enquiry is a tax authority checking your tax return. They are separate processes, though good records help with both.
Life Interest Trust

Life Interest Trust: Why They Matter More in 2026

Table of Contents

Quick answer: A life interest trust lets you pass on assets — most commonly the family home — while a spouse, partner, or other chosen person keeps the right to use them for their lifetime.

It’s one of the most common tools we discuss with clients doing estate planning, and in 2026 it’s become more relevant, not less: the nil-rate band has been frozen since 2009 and won’t move until at least April 2031, which means more ordinary estates are being pulled into inheritance tax purely because property and investment values have risen while the tax-free threshold hasn’t.

This guide covers how a life interest trust actually works, who the key people are, the real advantages and disadvantages, and what’s changed for 2026 that most articles on this topic haven’t caught up with yet.

What is a Life Interest Trust?

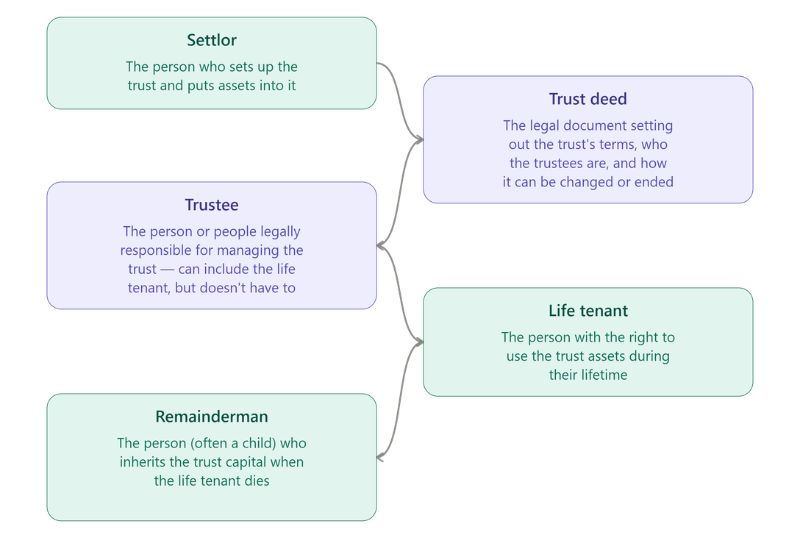
A life interest trust (sometimes called an interest in possession trust) is set up so that one person — the life tenant — has the right to use and benefit from the trust assets during their lifetime, without owning them outright. Most commonly this is a surviving spouse or civil partner, and the asset is usually the family home.

When the life tenant dies, the assets pass to the people named in the trust as the ultimate beneficiaries — the remaindermen. These are typically the children of the person who set up the trust, though they can be any beneficiaries the settlor chooses.

There are two important distinctions:

  1. The life tenant is not automatically the trustee. The trustees are the people who legally control and administer the trust; the life tenant simply has the right to benefit from it. A surviving spouse can be both, but doesn’t have to be.
  2. The life tenant generally cannot sell the trust property or give it away without the trustees’ agreement. This is what protects the remaindermen’s eventual inheritance — and it’s also the main practical restriction people find frustrating.

Quick Glossary

Life Interest Trust

Life Interest Trust Rule Updates

A few changes in force this year make this planning more, not less, worthwhile for the right estates:

1. Nil-rate bands are frozen until 2031

The standard nil-rate band stays at £325,000 and the residence nil-rate band at £175,000. As asset values rise and the thresholds don’t, more estates cross the line — a life interest trust can help ring-fence the family home and preserve both spouses’ allowances rather than letting everything land in one estate on second death.

2. Business and agricultural relief changed in 2026

100% relief now applies only to the first £2.5 million of combined qualifying business and agricultural property per person (transferable between spouses, so up to £5 million as a couple), with 50% relief above that. If business or farm assets are part of what you’re planning to put into trust, this changes the sums.

3. Pensions join the estate for IHT from 2027

Unused defined-contribution pensions will count toward your estate from next year, which is prompting many people to revisit their overall estate plan now rather than later — trusts included.

Life Interest Trust Advantages

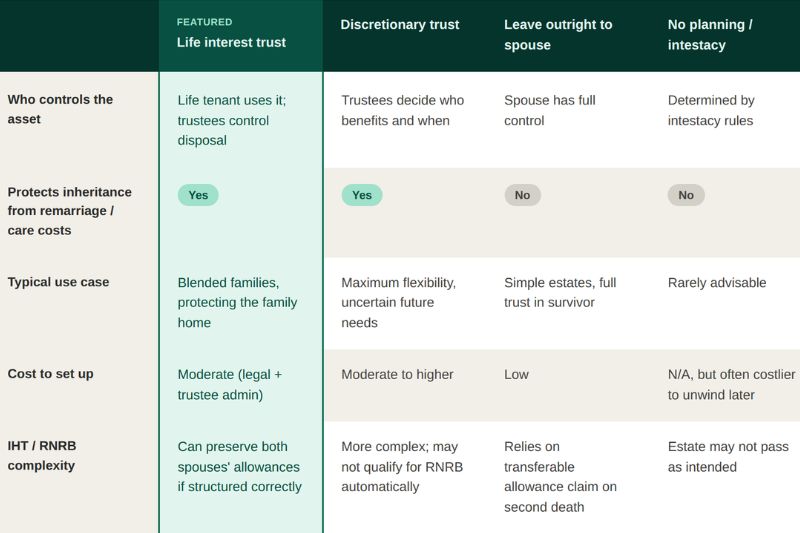
– Protects the asset while providing for a survivor: The life tenant can use the home or income from the trust for life, while the capital is protected for the next generation — useful where there’s a blended family and you want to provide for a second spouse without disinheriting children from an earlier relationship.

– Preserves the residence nil-rate band: Structured correctly, a life interest trust holding the family home can help both spouses’ residence nil-rate bands be used, rather than the full property value sitting in the survivor’s estate and only one RNRB being available.

– Protects against a survivor’s future decisions: Because the life tenant can’t sell or give away the capital without the trustees’ consent, the eventual inheritance is protected from being spent, gifted away, or lost — including if the survivor later remarries or needs long-term care.

Life Interest Trust Disadvantages

– Restricted control: The life tenant cannot sell, mortgage, or give away the trust property without the trustees’ agreement — even if their own circumstances change.

– Cost and complexity: Setting up and administering a trust involves legal and accountancy fees, and ongoing trustee duties. It’s generally only worthwhile where there’s a meaningful estate or a family home involved — a solicitor or accountant can tell you where that threshold sits for your circumstances.

– No automatic distribution on the life tenant’s death: If the life tenant is a surviving spouse, the remaindermen don’t inherit until that spouse also dies — even where children from an earlier relationship were the intended eventual beneficiaries.

– Income tax on trust income: The life tenant is generally liable for income tax on income arising from the trust, which needs factoring into their personal finances, not treated as free money.

– Delayed access for beneficiaries: Remaindermen typically get nothing until the life tenant dies — which can create family tension, particularly with stepchildren or where beneficiaries have their own financial pressures in the meantime.

Example: How the Numbers Actually Play Out

Take a couple, David and Sarah, who jointly own a family home worth £600,000 plus £100,000 in savings — a £700,000 estate.

1. Without Any Trust Planning

  • On David’s death, everything passes to Sarah under spouse exemption (no IHT due at that point).
  • But Sarah’s estate now holds the full £700,000.
  • On her death, only her own nil-rate band (£325,000) and residence nil-rate band (£175,000) — £500,000 combined — are available, unless David’s unused allowances are formally claimed and transferred.
  • If that claim is missed, £200,000 is taxed at 40%, a £80,000 bill.

2. With a Life Interest Trust

  • David leaves his half-share of the home (£300,000) into a life interest trust for Sarah, rather than to her outright.
  • Sarah retains full use of the home for her lifetime.
  • On her death, David’s share passes to their children as remaindermen, using David’s own nil-rate band directly rather than relying on a transfer claim.
  • This doesn’t necessarily save more tax than correctly claiming transferable allowances would — but it removes the risk of the claim being missed or mishandled by an executor years later, and it protects David’s share for the children even if Sarah later remarries or needs to fund long-term care.

Which Structure Fits Your Situation?

Which structure fits your situation

Is a Life Interest Trust Right for You?

Some questions worth working through before deciding:

  • Do you have a blended family, or want to provide for a spouse while protecting children’s eventual inheritance?
  • Is the family home (or another significant asset) likely to be affected by the frozen nil-rate bands?
  • Do you hold business or agricultural assets that the April 2026 relief changes affect?
  • Are you comfortable with the ongoing cost and administration of a trust versus simpler options like a straightforward will?

Quick Checklist Before You Decide

Before your first conversation with an accountant or solicitor about a life interest trust, it’s worth having answers to:

What is the current value of the asset(s) you’re considering putting into trust?

Is this a blended family situation, or a straightforward estate?

Do you or your spouse hold business or agricultural assets affected by the April 2026 relief changes?

Has anyone claimed (or will need to claim) a transferable nil-rate band from a previous death in the family?

Who would you want as trustees, and are they willing and able to take this on?

Is there a will already in place, and does it reflect what you’re planning?

Frequently Asked Questions

WHO PAYS TAX ON A LIFE INTEREST TRUST?

The life tenant is generally liable for income tax on income they receive from the trust. Inheritance tax treatment depends on how and when the trust was set up — get this checked, as older trust structures can sometimes disqualify the residence nil-rate band.

CAN A LIFE INTEREST TRUST BE REVOKED?

This depends on how the trust was written. Some are set up as revocable during the settlor’s lifetime; many, once the settlor has died, are fixed and cannot be unwound by the life tenant alone. Check the trust deed rather than assuming either way.

HOW DO I TERMINATE A LIFE INTEREST TRUST?

Termination routes generally include the life tenant’s death (which triggers distribution to the remaindermen), all beneficiaries agreeing and signing a deed, or a court order in disputed cases. Legal advice is essential before attempting this.

HOW DO I CHOOSE TRUSTEES FOR A LIFE INTEREST TRUST?

Look for people who understand your wishes, have the time and capacity to manage the trust properly, and can be trusted to act in the beneficiaries’ interests — this can be family, friends, or a professional trustee such as an accountant or solicitor.

Conclusion

A life interest trust isn’t a tax trick — it’s a way of separating who can use an asset from who eventually owns it, which matters most for blended families and for protecting the family home under frozen nil-rate bands.

It comes with real costs and restrictions, so it’s worth weighing against simpler options before committing. Get the structure right, with the right trustees and a deed that matches your actual wishes, and it can do exactly what it’s meant to: provide for who you want, in the order you want, without leaving it to chance.

We offer a free, no-obligation first consultation to look at your estate, your family situation, and whether a life interest trust — or another structure — makes sense for you.

sme accountant

Accounting vs Bookkeeping Service | 6 Key Differences

Table of Contents

Accounting vs Bookkeeping

Accounting vs Bookkeeping services are two different processes that are often confused. While the importance of accounting is the system of recording, classifying & summarizing financial transactions, the fundamentals of bookkeeping is the practice of recording & maintaining these transactions in a specific way.

Key Differences

1) Accounting provides an internal overview of a company’s financial status while bookkeeping tracks individual dealings.

2) Accounting is used to make business decisions, while bookkeeping is used to track accurate financial information.

3) Accounting uses Generally Accepted Accounting Principles (GAAP), while bookkeeping may use other methods.

4) Accounting must be audited, while bookkeeping does not need to be.

5) Accounting records money coming in and money going out, while bookkeeping tracks individual transactions.

6) Accounting is mainly used for larger companies, while bookkeeping can be used for any company.

What Is Accounting?

Part of the accounting process is recording, classifying, and summarizing financial transactions to provide information that is useful in making business decisions. This information can be used internally by businesses or externally by authorities and other interested parties.

The financial accounting process begins with the recording of transactions. This can be done manually or electronically. Once the operation has been recorded, they are then classified according to their type.

For example, money, credit card and invoiced transactions would all be classified as income, expenses, assets, or liabilities. After the transactions have been classified, they are summarized into financial statements. These reports show a company’s financial position, performance, and cash flow at a specific point in time.

How Accounting Can Help Your Business?

By completing transactions, businesses can keep a trail of their expenses and revenue, which can help them to make informed business decisions. Also, financial accounting uses (GAAP), which allows businesses to compare their performance.

Additionally, accountancy can help businesses prepare tax returns, which can save them tons of money. Overall in the long term, accounting is a valuable service for businesses of all sizes.

What is GAAP?

Is a set of cost accounting standards that are used in the United Kingdom. These standards provide a framework for financial reporting and help businesses compare their performance. They are also used by tax authorities to ensure that businesses are reporting their finances accurately.

Accounting

Types Of Accounting

There are four main types of accounting: financial accounting, management accounting, public accounting, and government accounting.

1. Financial Accounting

Is the activity of recording, classifying, and summarizing a company’s economic transactions to provide information that is useful in making business decisions. This information can be used internally by businesses or externally by investors, creditors, and other interested parties.

2. Management Accounting

Is the activity of providing reports to managers so that they can make informed decisions about how to run the business. This information includes things like budgeting, performance measurement, and forecasting.

3. Public Accounting

Is the activity of providing financial accounting services to clients such as individuals, businesses, or non-profit organizations. Public accountants may work for accountancy firms or they may work for accounting departments in larger companies.

4. Government Accounting

Is the activity of providing accounting services to governmental entities such as state, local, and federal governments. Government accountants may also work for accounting firms or they may work for accounting departments in larger companies.

What Are Financial Statements?

A financial statement is a summary of a company’s financial performance over a specific accounting history.

1. Balance sheet

The balance sheet shows a company’s assets, liabilities, and shareholders’ equity at a specific point in time.

2. Income statement

Shows a company’s revenues and expenses over some time.

3. Statement of cash flows

Shows how a company’s cash has changed over a period of time.

4. Statement of changes in equity

Shows how the company’s shareholders’ equity has changed over a period of time.

5 Accounting Mistakes To Avoid

1) Not keeping track of your fixed and variable expenses. If you don’t track your expenses, you won’t know how much money your firm making (or losing).

2) Not preparing a written budget is critical, it helps you follow your expenses, forecast future income statement and make sound financial decisions.

3) Not keeping accurate financial reporting can lead to a number of problems for your firm, including inaccurate tax returns and difficulty securing loans or lines of credit.

4) Not paying attention to cash flow data could lead to financial instability.

5) Not treating employees fairly can put a serious damper on the business and accounts. Employers have to treat them fairly and in return, you’ll have a productive workforce that will help your business grow.

What Qualification is Needed to be an Accountant?

The simple answer is no, you don’t need a degree to be an accountant. Postgraduate education is beneficial but not necessary, just like other professions. Instead, the majority of people in the sector have completed an AAT (Association of Accountants Technicians) course.

This certificate is often the min. requirement for accounting entries or for certified public accountants, which trains you the basics up to expert skills, across three levels. With this certificate, you’ll be able to pursue a career in accounts in a variety of interesting sectors like forensic accounting, public sector, private sector etc.

What Is Bookkeeping?

Bookkeeping is the recording of individual financial transactions. It can be done manually or using cost accounting software. The aim of bookkeeping is to ensure that financial records are accurate and up-to-date.

Bookkeeping is essential for businesses, as it helps them follow their financial position and make sound decisions based on accurate data. It also helps businesses prepare tax returns and manage their cash flow.

types of bookkeeping

Types Of Bookkeeping

There are two types of bookkeeping, single and double-entry bookkeeping.

Single entry system

Single-entry bookkeeping is a simple method where each financial transaction is recorded only once, either as a debit or a credit. This method is typically used by small businesses and individuals who have basic accounting needs.

Double entry system

Double-entry bookkeeping is a more advanced method where each financial transaction is recorded twice, once as a debit and once as a credit. This method provides a more accurate picture of a company’s financial health and is recommended for larger businesses with more complex accounting needs.

5 Bookkeeping Mistakes To Avoid

1) Not keeping track of expenses is one of the most common bookkeeping mistakes.

2) Reconciling your bank statements is essential for ensuring accuracy in your financial records and history.

3) Not tracking inventory and sales makes it difficult to determine how much money your company is making or losing.

4) Not registering transactions on time makes it difficult to keep track of your business’s financial data.

5) Not using double-entry bookkeeping. This involves using debits and credits to make sure that the accounting period are accurate. For example, can help prevent human error. It can also help make sure that transactions are accurate and complete, which is important when it comes time to file taxes.

What Qualifications do you Need to be a Bookkeeper?

You don’t need a degree or years of experience to apply for an entry-level position. However, you should have good math skills, a basic understanding of accounting or bookkeeping practices, and software knowledge of programs like QuickBooks, Xero, Kashflow or FreshBooks.

The best guide to obtaining a qualification in bookkeeping is through AAT. This gives you a strong overall grasp of accounting courses including bookkeeping, economics and account preparation.

Also, get some practical experience “bookkeepers work” or training before you choose a career to become a certified public accountant and look for an accountant or bookkeeper role in accounting firms, companies or professional bodies.

Conclusion

The difference between accounting vs bookkeeping is the processes. Bookkeeping is simply the process of recording the financial transaction in a specific way, while accountancy takes these recorded transactions and interprets them to provide useful information for making company decisions.

Accountants and bookkeepers can be invaluable partners if you’re looking for help with your financial analysis or want someone to manage your books. They’ll focus on everything from generating budgets to filing taxes so you have more time on other important tasks! Contact MH Services today.

pay less tax

6 Tips How To Pay Less Tax in UK Legally

Table of Contents

Pay Less Tax In UK Legally

In these difficult economic times, it’s no surprise that more and more people are looking for ways to pay less tax. The UK has one of the highest tax rates in the world, so most people are looking for ways to legally reduce their tax bills.

6 Ways To Save Paying Tax

These are the following tips you can apply before your tax return to pay less tax in the UK. Plus, we have a bonus paragraph on how to find an accountant or bookkeeper?

1. Tax code

Back to basics. How to pay taxes? Our tax advice is, to first check your tax code and ensure it is correct, otherwise, you could face a higher tax bill. If you get it wrong it could end up costing you over £100 a month.

2. Allowances

There are a number of tax allowances that you may be able to take advantage of in order to avoid paying too much tax, which may include the personal allowance, the marriage allowance, the capital gains tax allowance etc.

3. Pension contribution

Paying more pension contributions is one of the best ways to save tax. By contributing to a pension, you can take advantage of tax relief on your contributions, which means you pay less tax overall. In addition, many employers offer matching contributions, so you can get even higher value for your money.

4. Charity or gifting

Giving to a charity does more than make you feel good; it also saves tax money and lowers your self-assessment tax return burden, however it is only accessible by adding Gift Aid to the donation. In addition, you must keep all records of the charitable donations to reduce your taxable income.

5. Sacrifice income

If you’re looking for a way to pay less tax this year, sacrificing your salary might be an option and it is absolutely legal. There are many different types of arrangements in which employers and employees can agree so that both sides can benefit without having any financial loss e.g. medical insurance, gym membership, child care, car leasing etc.

Contact your payroll department for more details or our accountant for tax planning.

6. Employ a companion

In the UK, the personal allowance (£12,570) is a limit on how much you can earn to not pay taxes. If you are a self-employed or business owner and your spouse or partner doesn’t work or they’re unemployed you might consider employing them and dividing the salary of ‘Yours’ between the two people. By doing that, you can reduce your tax bill.

pay less tax

How much is the income tax rate?

Income tax is paid at a rate of 20% for most people. This means that for every £1 that you earn, you have to pay 20 pence in tax. However, higher earnings will result in higher tax payments.

How to find accountants or bookkeepers?

When it comes to accounts and bookkeepers, it’s important to find professionals who can help you keep your company finances in order.

Here are a few tips on how to find a good accountant and bookkeeper:

=> Check with the Better Business Bureau to see if any complaints have been filed against potential accounting or bookkeeping firms.

=> Interview several accounting or bookkeeping firms before making a decision. Be sure to ask about their experience and what services they offer.

=> Make sure the bookkeeping or accounting firm is licensed and insured.

=> Ask for a free consultation so you can get a feel for how the bookkeeping or accounting firm works.

=> Make sure you are aware of and understand the firm’s fees and billing practices before starting work.

=> Get referrals from other businesses.

Conclusion

In this article, we’ve outlined several ways that you can pay less personal tax in Manchester or in the United Kingdom. These include taking advantage of tax allowances, making pension contributions, donating to charity, and sacrificing income tax.

We’ve also provided tips on how to find good tax accountants or bookkeepers. By following these tips, you can save yourself hundreds or even thousands of pounds each year. Let us know in the comments if you have any questions about tax planning or how to reduce your tax bill.


self assessment tax return

5 Quick & Easy Self Assessment Tax Return Tips

Table of Contents

Filing your taxes might seem complicated, but with the right tips and advice it can be a breeze. In this blog post we will provide some quick self assessment tax return tips and tax saving ideas to help make the process as easy and stress-free as possible, but first, let’s talk about a self-assessment tax return.

What is a Self-Assessment Tax Return?

It is a process of declaring your income and paying the appropriate taxes to the government. It’s important to file your taxes on time and accurately, so you can avoid any penalties or fines.

Who should complete a tax return?

Self-assessment service is mandatory for anyone who has earned more than £1,000 in the former tax year.

Also, you should file a tax return if the following applies to you:

  • Employment earning [£12,570+]
  • Savings and investments [£10,000+]
  • Dividends [£14,570+]
  • Property rental [£1,000+]
  • Tips and commission [£2,500+]
  • Capital gains [£12,300+]
  • Pension scheme [£2,500+]

=> If you’re self-employed or in a business partnership, you must file a tax return also even if your income is below the taxable limit. This is because you still have to declare your revenue and pay income taxes on it.

=> If you’re not sure whether or not you need to file a tax return, it’s best to speak with accountants or look up GOV.UK.

How to File a Tax Return?

There are several ways to prepare and file a self-assessment tax form, and the best option will vary depending on your circumstances.

To start, it’s essential to gather all necessary financial documents, such as income statements, expense receipts, and any relevant tax forms.

A) One convenient option is to leverage online resources and tools, many of which are available on the HMRC website. HMRC’s online platform provides a user-friendly interface that guides you through the entire process, ensuring you fill out the necessary fields accurately.

If you’re not sure how to file it, or you need help preparing your return, there are many resources available online and on the HMRC website.

B) If you prefer personalized assistance, consulting with an accountant or tax specialist is another avenue to consider. These professionals possess in-depth knowledge of tax regulations and can offer valuable insights tailored to your specific situation.

MH Services, for example, provides a free consultation 24/7, making it easier for individuals to seek guidance at their convenience.

What if I Make an Error?

If you make a mistake on your tax return form, you can usually fix it by submitting an amended return. There is a time limit for amending your return [12 months] from the submission date.

However, it’s important to be accurate, as any mistakes can result in penalties or fines. You can do this by filing a new return or amending an existing one. There are several ways to fix your tax affairs, so it’s best to speak with an accountant or tax specialist for help.

self assessment tax return tips

5 Self Assessment Tax Return Tips

1. Plan ahead for tax payment

The best way to make a tax returns walk in a park is to create a plan [add notes to your calendar] and stick to it.

2. Gather your income tax bill

Before you file your return, you have to collect all the relevant invoices. This includes income receipts, tax-deductible expenses and any other relevant data. Make sure to have everything ready before you start filing, otherwise your self-assessment could turn into a nightmare. If you are not sure what forms are needed contact an accountant.

3. Use an accountancy tax software

Using tax software can be a great way to file and then pay tax online quickly and easily. The software will ask you a series of questions about your income and expenses, and then generate the appropriate tax returns for you. There are many different options available on the software market, so find one that suits your needs and preferences.

4. Claim tax relief on expenses

One of the best ways to reduce your tax bill is to claim any eligible expenses. This could include things like travel expenses, home office costs, vehicles, child benefits or other taxable benefits. Make sure to keep track of all of your expenses throughout the year, and be sure to include them in your tax relief.

5. Get accountant help

If you are feeling overwhelmed or confused about the self-assessment process, don’t be afraid to ask for help. There are many tax return resources available, including accountant professionals, online self-assessment forums, and even accountancy software support. You don’t have to do it all alone – get the help when you needed!

How to Pay Income Tax?

Double-check the amount you have to pay. Make a one-time payment or set up a payment plan to spread the cost.

Income taxes are paid in one of two ways:

A) By deduction from your salary

B) By self-assessment, if you are self-employed or you have an income from the above-mentioned source

When to pay the tax bill?

The due date for the previous tax year is no later than the 31st of January.

What to declare?

Make sure, you are aware of all types of income e.g. property income, self-employed income and other income. There are penalties for failing to declare all relevant revenues.

Conclusion

Filing a self-assessment return can seem daunting, but with the help of the right accountancy service it doesn’t have to be. Our team has years of experience preparing and filing self-assessment tax returns for sole trader, self-employed people and trader business owners. We understand the tax year process inside out, so you can rest assured that your taxable income will be filed accurately and on time.